Standard cost is the planned cost per unit, set from the recipe, the expected yield and standard prices for ingredients, labor and overhead. Actual cost is what a batch really cost once the real ingredient lots, hours and good output are known. Food manufacturers use standard cost to quote and plan, actual cost to see true margin, and the gap between them to find waste.
This guide defines the terms, compares the common inventory costing methods, walks through a batch example and shows where yield loss hides. If you are choosing tools, see our overview of food manufacturing software.
Standard Cost vs Actual Cost: What Each Means
The two are not rivals. A standard cost is a target you set before production. An actual cost is a result you calculate after it. The useful work is in comparing them.
| Method | What it measures | Best used for | Watch out for |
|---|---|---|---|
| Standard cost | Planned cost per unit from the recipe, standard prices, standard hours and expected yield | Quoting, budgeting, setting prices | Goes stale when ingredient prices or yields change and nobody updates it |
| Actual cost | What a specific batch cost, using the lots and hours actually consumed, divided by good units made | True batch margin, finding waste | Needs lot-level cost and real yield captured at batch completion |
| FIFO inventory costing | Assumes the oldest purchase cost is consumed first | Valuation when prices move steadily | A bookkeeping assumption, not physical rotation |
| Weighted-average costing | Blends purchase costs into one average cost per unit | Simple valuation across many receipts | Smooths price swings, so it can hide a single expensive lot |
Which valuation method you use for the books is an accounting decision, so confirm it with your accountant. In QuickBooks Desktop Enterprise, for example, you can choose FIFO costing instead of average cost. Note that FIFO costing is not the same as FIFO stock rotation on the floor; we explain the difference in our guide to FEFO vs FIFO.
How Food Yield Changes Unit Cost
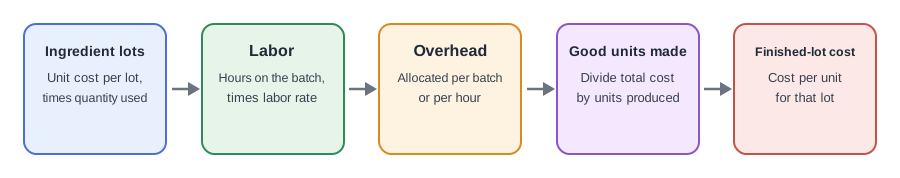
Food yield (also called production yield) is the share of input that becomes sellable output. Trim, evaporation, spillage, rework and QA rejects all reduce it. Because unit cost is total batch cost divided by good units, a yield drop raises cost on every unit even when ingredient prices and labor hours stay exactly the same.
The formula is:
Unit cost = (ingredient cost + labor + overhead) ÷ good units produced
Two things follow. First, the denominator must be good units, not units started. Second, overhead is usually allocated by hours or by batch, so a slow batch carries more of it per unit.
A Worked Batch Example
The numbers below are illustrative. Say a plant makes a 1,000-unit batch of sauce. The standard assumes 5 labor hours at $22 and overhead of $15 per hour. The actual batch ran 6 hours and lost 80 units to trim and a rejected hold.
| Line | Standard (1,000 units) | Actual (920 good units) |
|---|---|---|
| Ingredients | $400.00 | $412.00 |
| Labor | $110.00 (5 h) | $132.00 (6 h) |
| Overhead | $75.00 | $90.00 |
| Total batch cost | $585.00 | $634.00 |
| Cost per unit | $0.585 | $0.689 |
Unit cost rose about $0.104, roughly 18 percent. Splitting it shows where the money went: if the same $634 had produced 1,000 units, cost would have been $0.634, so about $0.049 per unit came from higher input cost and extra hours, and the remaining $0.055 came from losing 80 units of yield. Without actual costing, a spreadsheet would still say $0.585 and the margin problem would stay invisible.
Reading Variance Between Standard and Actual
A variance is the difference between standard and actual. Splitting it by cause tells you who owns the fix.

- Price variance: the ingredient lot cost more or less than the standard price. Owner: purchasing.
- Usage variance: more ingredient was consumed than the recipe calls for. Owner: production.
- Labor variance: more or fewer hours than the standard, or a different labor rate.
- Yield variance: fewer good units than planned from the same inputs. Owner: production and QA, because rejects and holds count here.
How to Move From Standard to Actual Costing
- Write down a standard cost per recipe: ingredients, hours, overhead rate and expected yield.
- Capture the real unit cost on each received ingredient lot.
- Record labor hours and the lots actually consumed in each batch.
- Record good units at batch completion, not units started.
- Calculate actual unit cost and compare it with standard every batch or every week.
- Update standards on a schedule so they do not drift.
Where Costing Fits Next to Your Accounting System
Your accounting system remains the ledger. The production and traceability layer is where lot, batch and yield data are captured, so cost can be attached to the right lot. With IONI's optional cost module, a received lot can carry a unit cost, and when a batch is completed the finished lot's unit cost is the consumed cost plus labor plus overhead divided by the quantity produced, provided every consumed input has a cost. COGS and margin can then be sent to QuickBooks as a journal. IONI runs on top of the QuickBooks you already have; it is not a replacement for it. For more, see recipe and food costing software and manufacturing software that works with QuickBooks.
FAQ
What is the difference between standard cost and actual cost?
Standard cost is the planned cost per unit, set in advance. Actual cost is what a batch really cost, based on the lots, hours and good output recorded. Comparing the two reveals price, usage and yield problems.
What is food yield and why does it matter for cost?
Food yield is the share of input that becomes sellable product. Because batch cost is divided by good units, lower yield raises the cost of every unit.
Is inventory costing the same as inventory rotation?
No. Inventory costing (FIFO, weighted average) is an accounting valuation method. Rotation (FIFO or FEFO) is the physical order in which stock is used or shipped.
Should a small food manufacturer use standard or actual costing?
Most use both: standards for quoting and planning, actual costs to check real margin. Start with standards on your top recipes, then add lot-level actuals.
How often should standard costs be updated?
Review them on a fixed schedule, such as quarterly, and any time a major ingredient price or yield changes materially.
Last updated: October 14, 2026
Capture lot cost and batch yield where production happens. Explore IONI's production and traceability software for food manufacturers.